Personal Finance System: Budget, Save, Invest, Pay Off Debt
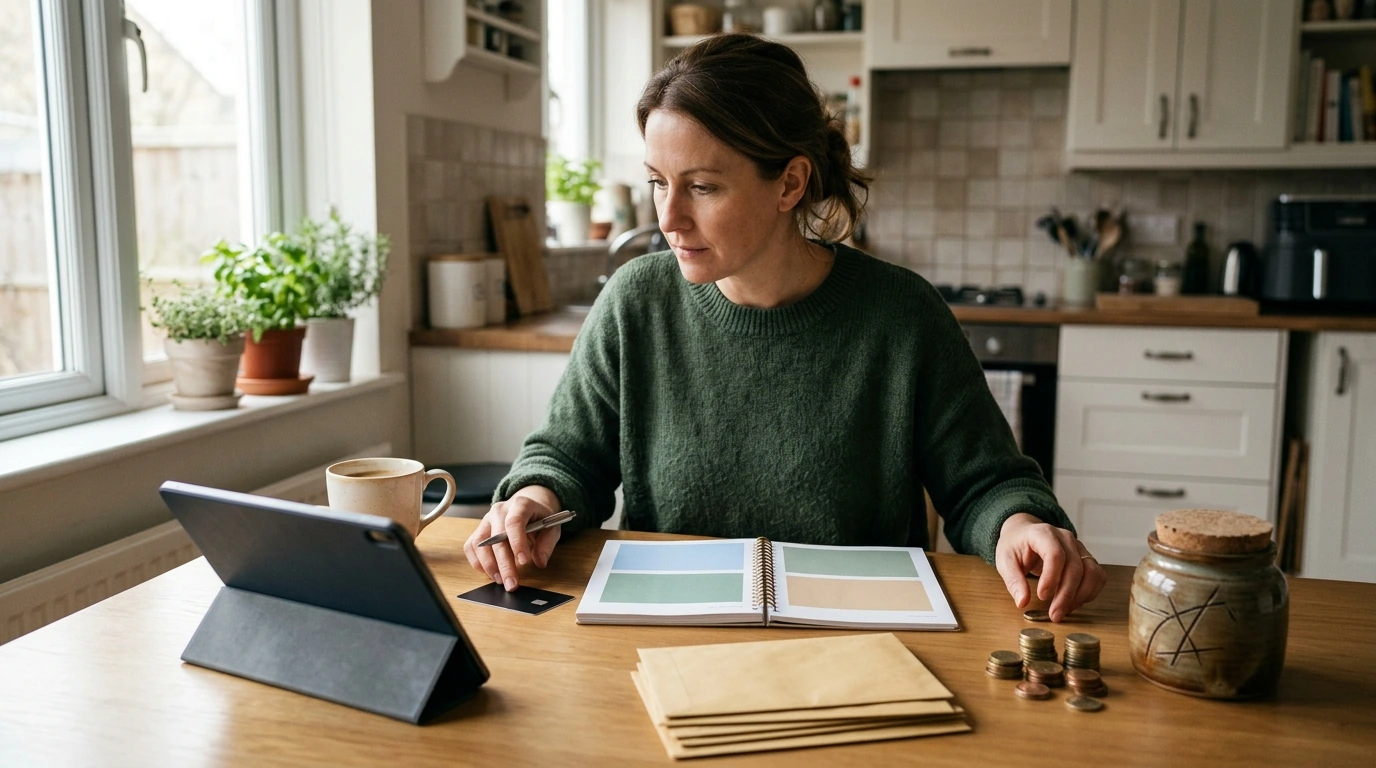
Personal Finance Made Easy: A Practical Path to Budgeting, Saving, Investing, and Debt Freedom
Money feels complicated when goals compete—bills, debt, saving, and investing all pulling in different directions. A simple, repeatable system can turn financial stress into clear next steps. The framework below breaks personal finance into four skills—cash flow, safety buffers, smart debt payoff, and long-term growth—so progress is measurable and sustainable.
Start with clarity: goals, numbers, and one weekly money check-in
Momentum comes from choosing a small set of priorities and tracking just enough to stay honest. Start by picking 1–2 priorities for the next 90 days—like building a starter emergency fund, paying off one credit card, or automating savings.
Next, list monthly take-home income and review the last 30–60 days of spending. The goal isn’t perfection; it’s visibility. Use “good enough” categories such as housing, food, transport, subscriptions, debt, and savings so you don’t get stuck building a complicated spreadsheet you won’t revisit.
Finally, set a 20–30 minute weekly money check-in. Look at balances, upcoming bills, and pick one next action: reduce one expense, make one extra payment, or increase one automatic transfer. Over time, that weekly touchpoint becomes the habit that keeps everything else on track.
Budgeting that sticks: choose a method and automate the basics
A workable budget matches how you naturally make decisions. Three reliable options:
- Zero-based budgeting: every dollar gets an assignment (great for detail-lovers).
- 50/30/20: needs/wants/savings (great for simplicity).
- Envelope-style: pre-set limits for problem categories (great for curbing overspending).
Whichever method you choose, automation does the heavy lifting. Schedule fixed bills and savings transfers right after payday to reduce decision fatigue. Then add “true expenses”—annual fees, car repairs, gifts, medical bills—as monthly sinking funds so predictable costs don’t become surprise debt.
If income or expenses vary, include a buffer category. Think of it as shock absorption: a place where you can park extra money in good months and pull from it in tight months.
Simple monthly budget template (example)
| Category | Planned | Actual | Notes |
|---|---|---|---|
| Take-home income | $3,500 | $3,500 | Paydays deposited |
| Housing & utilities | $1,350 | $1,410 | Higher electric bill |
| Food | $450 | $520 | Reduce takeout next month |
| Transport | $300 | $280 | Gas lower than expected |
| Subscriptions | $60 | $60 | Review streaming |
| Debt payments | $500 | $500 | Minimums + extra |
| Emergency fund | $200 | $200 | Automatic transfer |
| Investing | $250 | $250 | Retirement contribution |
| Fun/misc. | $390 | $280 | Rolled remainder to savings |
Saving without feeling deprived: build safety in layers
Savings works best when it’s layered, not all-or-nothing.
- Layer 1: Starter emergency fund. Often 1–2 weeks of expenses. The point is to stop new debt when small surprises hit.
- Layer 2: Full emergency fund. Commonly 3–6 months of essential expenses, adjusted for job stability, dependents, and health needs.
Use separate buckets so you don’t accidentally spend “emergency money” on planned costs. An emergency fund is for job loss, urgent medical bills, or necessary repairs. Sinking funds are for predictable expenses like holidays, insurance deductibles, or annual renewals.
If saving feels tight, increase gradually. Small bumps after a raise, tax refund, or debt payoff are often painless because your lifestyle doesn’t have time to expand and absorb the difference.
Debt management: pick a payoff strategy and protect your progress
Debt becomes manageable when it’s organized. List each debt with balance, interest rate, minimum payment, and due date. Set autopay for minimums to avoid late fees and missed payments, then focus your extra money on a single target.
- Avalanche method: pay extra toward the highest interest rate first to minimize total interest.
- Snowball method: pay extra toward the smallest balance first to build motivation and quick wins.
If interest rates are high, look for ways to reduce the burden: negotiate rates, consider a balance transfer (watch fees and the promotional payoff window), or refinance qualifying loans. Whatever strategy you choose, avoid the “payoff then re-charge” trap by pairing extra payments with spending guardrails and a starter emergency fund.
Investing basics: start simple, stay consistent, think long-term
For trustworthy basics on managing cash flow and building a budget, the Consumer Financial Protection Bureau (CFPB) is a solid starting point. For investing fundamentals, see Investor.gov. For retirement plan details and contribution rules, reference the IRS retirement plans resources.
A realistic 30-day plan you can repeat every month
A guided option for building the full system step by step
If a structured roadmap would help, a dedicated guide can connect budgeting, saving, investing, and debt payoff into one simple plan with checklists and templates. The Personal Finance Made Easy Ebook – Budgeting, Saving, Investing & Debt Management Guide for Financial Freedom is designed for practical week-by-week actions so progress stays steady even during busy weeks.
Money habits also improve when stress is handled proactively. If anxiety or mental overload makes it hard to follow through, consider pairing your plan with Break the Tension: Stress Relief Techniques for quick resets that make it easier to stick to budgets and payoff routines.
FAQ
How much should go to savings vs. debt payoff?
Cover all minimum payments first, then build a small starter emergency fund so new surprises don’t push you back into debt. After that, send most extra cash to high-interest debt while keeping a modest automatic savings transfer to protect momentum.
What if income is irregular?
Budget from a conservative baseline (your lowest typical month), prioritize essentials, and keep a buffer category to smooth swings. When extra income comes in, sweep it in a set order—catch up essentials, fund near-term sinking funds, then add to debt payoff and savings.
How can investing start with a small amount?
Start by automating a small contribution per paycheck, especially if an employer match is available. Use low-cost diversified options and increase the amount after each debt milestone so investing grows naturally as obligations shrink.



Leave a comment